Jumbo Home Loans in Florida
Waterfront Tampa, Naples, the beaches, Miami and the islands: Florida’s jumbo market is where the state’s insurance questions and loan taxes meet lender-by-lender underwriting. We place the file where its shape fits, with the documentary stamps, intangible tax and a realistic insurance quote in the numbers from day one. Licensed statewide, in all 67 counties.
Florida Mortgage Broker License MBR3694 and Mortgage Lender License MLD2100. NMLS #1925352.
Jumbo in Florida, 2026
Jumbo threshold
Above $832,750 ($990,150 in Monroe)
Typical credit score
700 and up; best pricing from about 760
Down payment
Commonly 10 to 20 percent
State taxes on the loan
Documentary stamps $0.35 per $100 plus 0.2% intangible
Closing
Title company, mobile notary or remote online notarization
$832,750
Loans above this are jumbo, outside Monroe
700+
Typical minimum credit score, lender-set
67
Florida counties, licensed statewide
4.9
Average of 5,300+ Google reviews
Big loans, salt air and a tax that scales.
A Florida loan is jumbo above $832,750 in 2026, except in Monroe County, the Keys, where the limit is $990,150. Above the line, Fannie Mae and Freddie Mac step aside and private lenders underwrite to their own rules: typically a 700 score with the best pricing from 760, 10 to 20 percent down, six to eighteen months of reserves and full documentation. Most jumbo programs charge no monthly mortgage insurance at any down payment, though requirements vary by lender, program and loan-to-value.
Florida adds two state layers that scale with the loan. The documentary stamps and intangible tax, together about $0.55 per $100 of the mortgage, come to roughly $5,500 on a $1,000,000 loan. And the insurance bundle, wind cover and flood where the maps require it, is both a real cost and an underwriting input: on waterfront collateral, the insurer’s appetite can shape the deal as much as the lender’s. We put both in the first quote.
This page covers jumbo loans in Florida. The jumbo hub explains the market itself; conventional in Florida covers everything under the line; and buying in Florida and our Florida page round out the state.
What jumbo lenders ask for, and what Florida adds.
There is no agency rulebook above the line; these are the ranges we see across the jumbo lenders we work with. The last column is the Florida layer.
| Requirement | Typical range | In Florida |
|---|---|---|
| Credit score | Usually 700; best pricing from 760; a few lenders consider high 600s with compensating factors | The biggest lever on the rate at this size |
| Down payment | Commonly 10 to 20 percent; some programs hold 10 percent to a set loan amount | Second-home jumbo, a Florida staple, usually prices from 20 percent down |
| Cash reserves | Often 6 to 18 months of the full payment | The payment includes Florida’s insurance bundle, so the reserve figure is larger here |
| Documentation | Full income and asset documentation; self-employed files need two years of returns | Relocating executives, retirees with portfolio income and business owners are the typical files |
| Appraisal | One full appraisal; a second on larger loan amounts at many lenders | Waterfront comps are thin and seasonal; we build the comp book before the visit |
| Mortgage insurance | Most programs charge none at any down payment, though it varies by lender, program and loan-to-value | No state wrinkle; wind and flood cover is priced on your specific property |
Ranges reflect the jumbo lenders we work with; each writes its own rules, which is why the same file prices differently across them.
Three Florida jumbo files we see most.
Different shapes, different lenders. All three can close at a title company, with a mobile notary, or fully online.
Buying
Waterfront and the golf corridors
Naples, Sarasota, the beaches, Boca and the islands: purchases above the line where the appraisal, the insurance binder and the underwrite all need managing at once. That coordination is the actual service.
Second homes
The northern money file
A second home on the Gulf bought from Chicago or New York: jumbo second-home pricing, usually from 20 percent down, with reserves and the insurance bundle in the math. We run it by phone and e-signature, and Florida lets you close remotely.
Refinancing
A better jumbo
Jumbo spreads between lenders are wide, and insurance repricing has changed many Florida payments. A refinance quote re-shops both the rate and the structure; the state taxes on the new loan go into the break-even honestly.
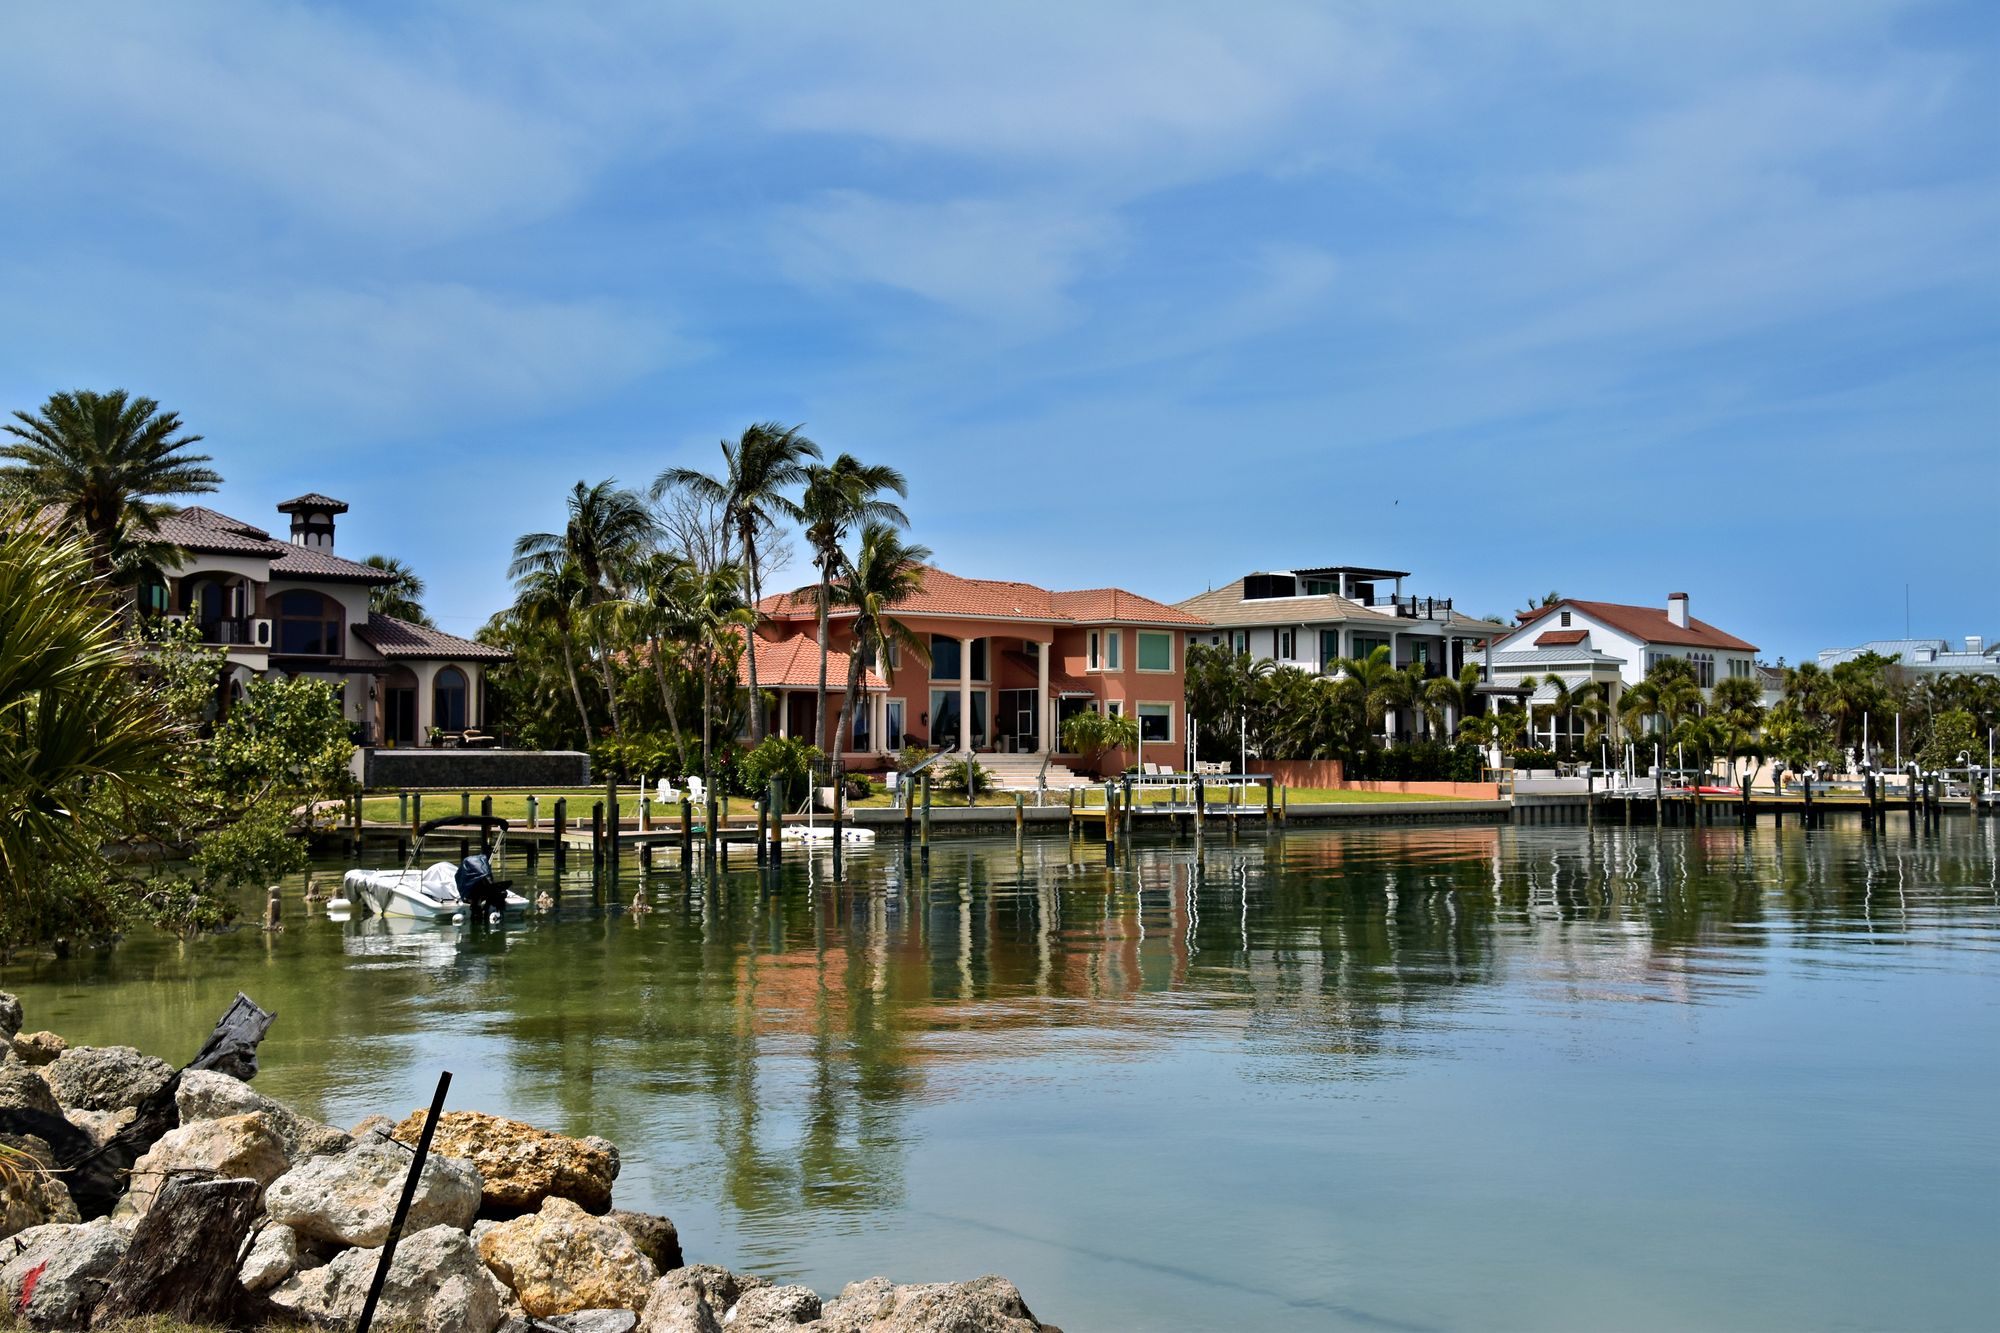
On Florida waterfront, insurance underwrites the deal with you.
A jumbo lender’s questions about a Gulf-front house are the insurer’s questions: the roof’s age and shape, opening protection, elevation, flood zone. The answers set the premium, the premium sets the escrow, and the escrow feeds the debt-to-income ratio, so a surprise binder a week before closing can reprice the whole file. We collect the wind mitigation and elevation facts at the start and get the quote bound early.
The reward for the discipline is a market that genuinely competes: most jumbo programs charge no monthly mortgage insurance (requirements vary by lender, program and loan-to-value), pricing between lenders is wide enough to shop, and Florida lets the closing happen at a title company, with a mobile notary, or fully online from another state. The file just has to be built in the right order.
Pensacola to the Keys
Jumbo purchases and refinances closed at a Florida title company, with a mobile notary, or fully online by remote notarization.
Six Florida details on a jumbo file.
What the state changes at this loan size. All of it appears on your Loan Estimate from the start.
01
Taxes that scale
Documentary stamps at $0.35 per $100 plus the 0.2 percent intangible tax: about $5,500 on a $1,000,000 mortgage, buyer-paid, and due again on a refinance. In the first quote, always.
02
Monroe’s higher line
The Keys’ conforming limit is $990,150, so some island loans that look jumbo are not. We check before placing the file.
03
The insurance bundle
Wind cover, flood where required, bound early because the premium feeds the ratio. Roof age and opening protection move the number materially.
04
Thin waterfront comps
A second appraisal is common on larger loans, and waterfront comparables are seasonal. We brief the appraisers with a real comp book rather than hoping.
05
Condo towers
Jumbo condo files add the project review: budget, reserves, inspections and the association’s insurance. Post-2022 Florida reviews are substantive, and we start them on day one.
06
Close from anywhere
Title company, mobile notary, or remote online notarization, which Florida allows; most northern buyers never fly down for the signing.
What would the payment look like?
Set a price above the limit and your down payment. Most jumbo programs charge no monthly mortgage insurance, so the payment is principal, interest, taxes and Florida’s insurance bundle.
The U.S. mortgage market right now.
National average conforming rates from the Federal Reserve Bank of St. Louis FRED database (the Freddie Mac survey for conventional, the Optimal Blue indices for FHA and VA), shown as third-party market benchmarks, not MortgagePros pricing. They describe conforming, FHA and VA loans, not jumbo pricing, which each lender sets on its own; the jumbo figure that matters is the one quoted on your file.
Conventional 30-year fixed, U.S. average
7.40%
FHA 30-year fixed, U.S. average
7.18%
VA 30-year fixed, U.S. average
7.09%
Sources: Freddie Mac Primary Mortgage Market Survey (conventional, 30-year national average, week of Oct 8, 2026) and Optimal Blue Mortgage Market Indices (FHA and VA, 30-year national averages as of Oct 8, 2026), distributed through FRED, Federal Reserve Bank of St. Louis; the figures and dates refresh automatically from the source. These are third-party market benchmarks, not MortgagePros rates and not an offer of credit. Your rate and APR depend on your credit, loan type, property and lock date.
How a Florida jumbo works with us.
Four steps, one licensed pro, a Florida closing wherever you are.
1
The file and the collateral, mapped
Income, assets, reserves, and the property’s insurance facts, gathered before anything is ordered.
2
Placed, then priced
The file goes to the lenders whose boxes fit it, with the state taxes and the insurance quote in the comparison.
3
Appraisal and binder in parallel
Comp book built, appraisals ordered early, the wind and flood cover bound before underwriting needs it.
4
Close anywhere
Title company, mobile notary or fully online. The taxes appear on the closing statement exactly as quoted.
Ready to price a Florida jumbo?
A Florida-licensed pro maps your file against multiple jumbo lenders, with the state taxes and a realistic insurance quote in the numbers. Free, and it starts without a hard credit pull.
Jumbo loans in Florida, answered.
The questions Florida jumbo borrowers ask us most. If yours is not here, a licensed pro will answer it directly, with no obligation.
When is a loan jumbo in Florida?
Above $832,750 for a one-unit home in 2026 everywhere except Monroe County, where the limit is $990,150. The FHFA resets the figures each year. Below the line, conventional in Florida applies, and conforming terms are usually the cheaper answer when you can structure under it.
How much do the state taxes add on a jumbo?
Documentary stamps at $0.35 per $100 plus the intangible tax at 0.2 percent, together about $0.55 per $100 of the mortgage: roughly $5,500 on a $1,000,000 loan, buyer-paid, and due again on a refinance. They are itemized on the Loan Estimate from the first quote.
Does waterfront insurance affect my approval?
Directly: the wind and flood premiums sit in the escrow, and the escrow feeds your debt-to-income ratio, so an expensive binder can reprice the file. We gather the roof, mitigation and elevation facts at the start and bind cover early, which is the difference between a smooth file and a scramble.
Can I buy a Florida second home with a jumbo loan?
Yes, it is one of the most common Florida jumbo files. Second-home jumbo usually prices from 20 percent down with reserve requirements on top, and the whole process, including the closing, can run remotely; Florida permits remote online notarization.
Is there mortgage insurance on a jumbo loan?
Usually not: most jumbo programs charge no monthly mortgage insurance at any down payment, though requirements vary by lender, program and loan-to-value.
Do I have to come to Michigan?
No, and you may not need to come to Florida either: your licensed pro handles the loan by phone, email and e-signature, and Florida allows closings at a title company, with a mobile notary, or fully online.
Talk to a Florida-licensed pro about a jumbo loan.
Tell us what you are looking to do and where in Florida. A licensed pro will call back, usually the same business day. Asking does not start a loan or require a hard credit pull.

Prefer to talk?
248-416-1361
Open 24/7. Ask for your pro by name.

Visit our office
880 W. Long Lake Rd, Suite 300
Troy, Michigan 48098, just off I-75. Free parking.

Licensed and reviewed
Florida Mortgage Broker License MBR3694 and Mortgage Lender License MLD2100. NMLS #1925352. Rated 4.9 across 5,300+ Google reviews.