Jumbo Home Loans in Michigan
If you’re looking to purchase a high-value property in Michigan, a jumbo home loan may be the financing solution you need. At MTGPros, we help homebuyers navigate the complexities of jumbo loans, ensuring you secure the right mortgage for your luxury or higher-priced home.
Licensed in 39 states from our Troy headquarters. Rated 4.9 across 5,200+ Google reviews. Quotes are free and start with no hard credit inquiry.
The 2026 conforming limit in Michigan
$832,750
Borrow more than this for a one-unit home anywhere in Michigan and you are in jumbo territory.
High-cost counties in Michigan
None; every county uses the baseline
Two-unit limit
Higher; ask your pro
Set by
FHFA, each November
The limit applies to the loan amount, not the price. A larger down payment can keep a purchase conforming, and we run that comparison every time.
2019
Founded in Troy, Michigan
300+
Licensed loan officers on the team
4.9
Average of 5,200+ Google reviews
39
States licensed, headquartered here
What is a Jumbo Home Loan?
A jumbo home loan is a type of mortgage designed for properties that exceed the conforming loan limits set by the Federal Housing Finance Agency (FHFA). In most areas, this limit is $832,750 for single-family homes, but in high-cost areas, the limit may be higher. If your desired loan amount is above these limits, a jumbo loan will provide the necessary financing.
Benefits of a Jumbo Home Loan
01
Higher loan amounts
Jumbo loans allow you to finance luxury homes, large properties, or homes in competitive real estate markets without being restricted by traditional loan limits.
02
Competitive interest rates
While jumbo loans may have slightly higher interest rates than conventional loans, many lenders offer competitive terms based on your creditworthiness.
03
Flexible terms
Choose between various loan options, including fixed-rate and adjustable-rate mortgages, depending on your long-term financial goals.
04
No PMI
Unlike some conventional loans, jumbo loans often do not require private mortgage insurance, even if you make a down payment of less than 20%.
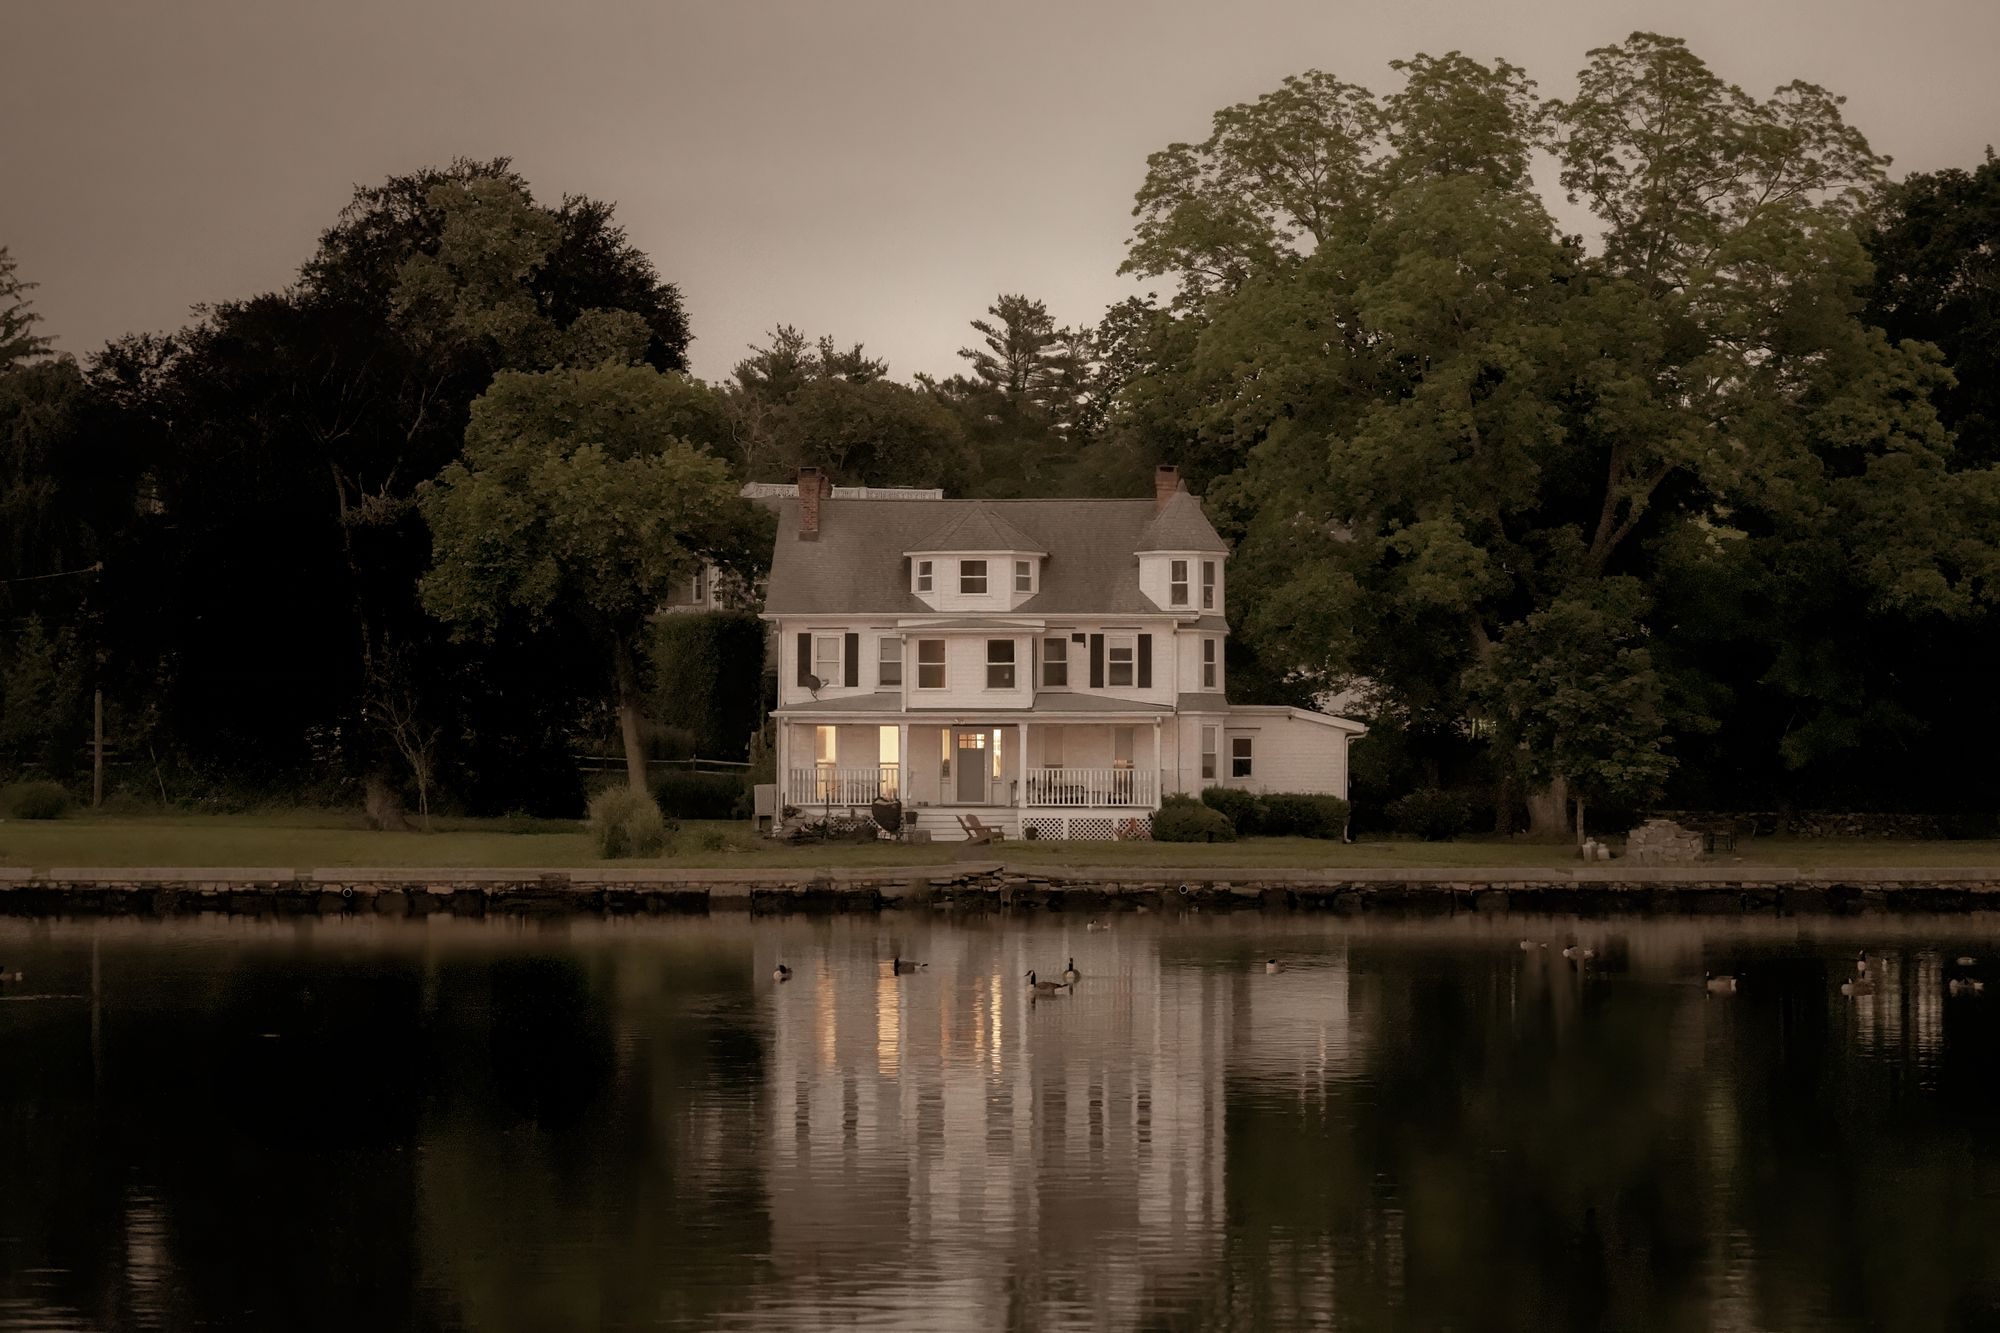
Lakefront and the Oakland County estates
Bloomfield Hills, Birmingham, Grosse Pointe and the lakeshore: in Michigan a jumbo loan starts above $832,750.
Who Qualifies for a Jumbo Home Loan?
To qualify for a jumbo home loan, lenders typically have stricter requirements due to the higher loan amounts and increased risk. These include:
- Excellent credit score: Most lenders require a credit score of 700 or higher, although some may consider borrowers with slightly lower scores.
- High-income and assets: Lenders will look for proof of stable, high-income, and liquid assets to ensure you can cover larger monthly payments.
- Low debt-to-income (DTI) ratio: A DTI ratio below 43% is preferred, though some lenders may allow slightly higher ratios for well-qualified borrowers.
- Substantial down payment: While down payments vary by lender, you may need to put down 10% to 20% or more, depending on the loan amount and your financial profile.
How Does the Jumbo Loan Process Work?
Four stages, one licensed pro, and you always know what happens next.
1
Pre-approval
Start by getting pre-approved for a jumbo loan to determine how much you can borrow. This will also give you an advantage when making offers on high-value homes.
2
Find a home
With pre-approval in hand, you can begin searching for luxury homes or properties that require jumbo financing.
3
Loan application
Once you’ve found your property, we will help you submit a loan application and provide the necessary financial documents.
4
Closing
After your loan is approved, we’ll guide you through the closing process, ensuring all details are handled smoothly so you can enjoy your new home.
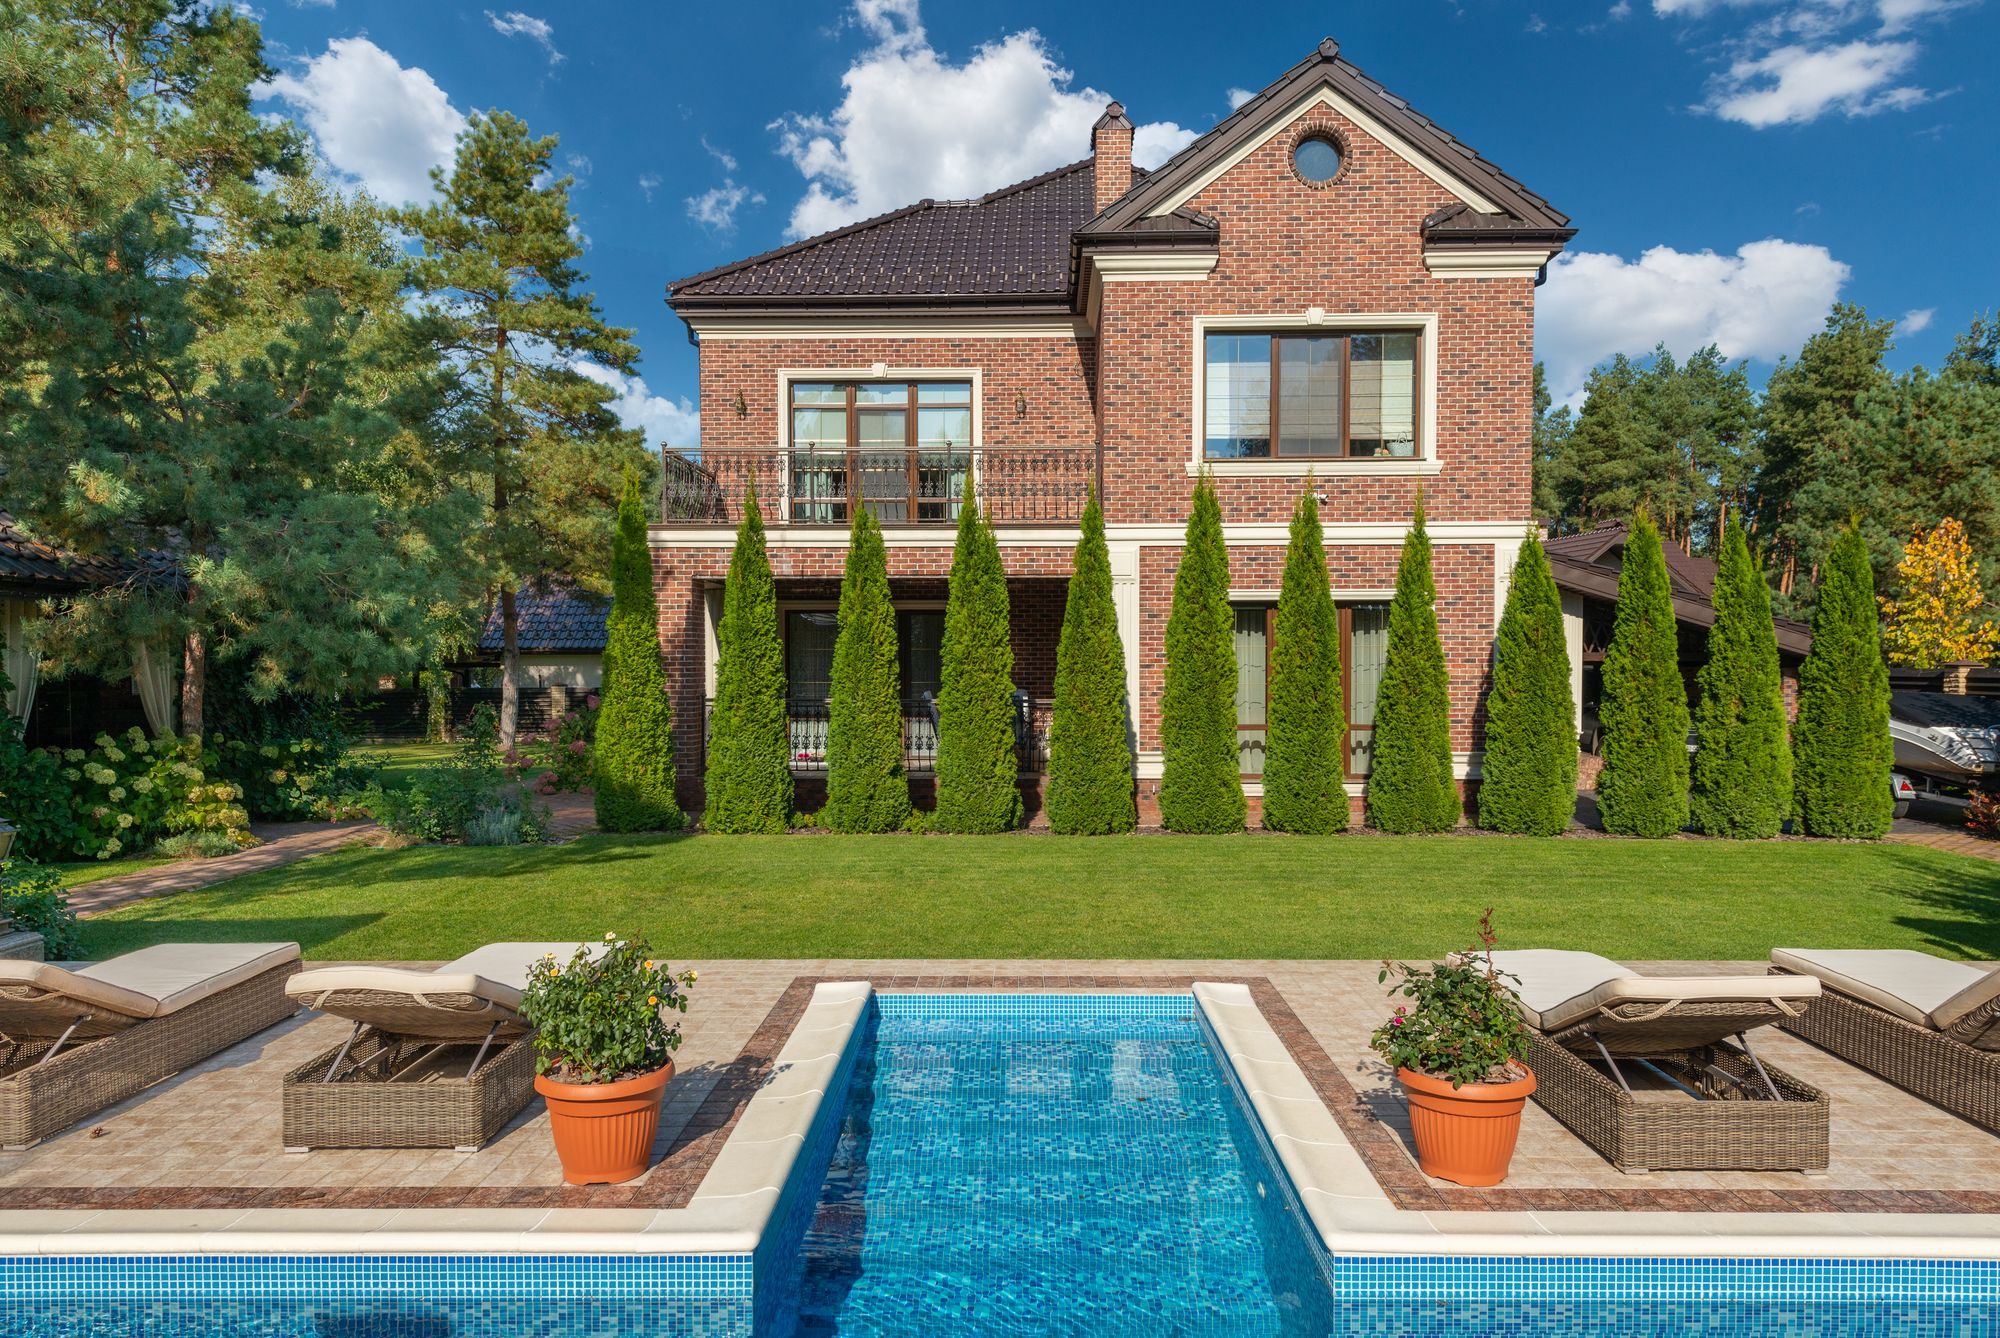
In Michigan, a jumbo loan starts above $832,750.
That covers the Oakland County estates, the Grosse Pointe lakefront, Ann Arbor’s upper end and the bigger places on Michigan’s inland lakes. Above that line, each lender sets its own rules.
As a broker we place the loan with the lender whose rules fit your income and reserves, which is often the difference between a clean approval and a stack of conditions.
Is a Jumbo Loan Right for You?
A jumbo loan is ideal if you’re purchasing a home that exceeds conventional loan limits. However, it’s important to consider the higher qualifications and ensure that you can comfortably manage the larger mortgage payments. If you meet the credit and income requirements, a jumbo loan could provide the financing you need for your dream home.
What would the payment be?
Set a price above the limit and choose Jumbo as the loan type. Most jumbo programs charge no monthly mortgage insurance, though requirements vary by lender, program and loan-to-value, so the payment is usually principal, interest, taxes and insurance.
Four things that are different about buying in Michigan.
They shape every jumbo loan we close in the state, and the first one catches buyers from elsewhere off guard.
01
Your property tax bill resets when you buy
Michigan caps how fast a home’s taxable value can rise each year, and that cap comes off when ownership transfers. The seller’s bill reflects their capped value; yours will be based on the current state equalized value, which can be materially higher. Budget from the SEV, not the seller’s bill, and file the Principal Residence Exemption, which removes up to 18 mills of school operating tax on the home you live in.
02
Transfer tax is the seller’s cost by default
Michigan charges $3.75 per $500 of price to the state and $0.55 per $500 to the county, and the seller pays unless the purchase agreement says otherwise. Buyers pay recording fees and title charges instead, which are far smaller.
03
Loan limits are simple here
Every Michigan county uses the national baseline: $832,750 for a conforming loan and $541,287 for an FHA loan on a one-unit home in 2026. There are no high-cost counties in the state, so the limit is the same in Troy, Detroit, Lansing and Ann Arbor.
Michigan Counties We Serve
MTGPros provides jumbo loan services throughout Michigan, including:
Metro Detroit Area
Wayne County – Detroit, Dearborn, Livonia, Westland
Oakland County – Troy, Bloomfield Hills, Birmingham, Royal Oak
Macomb County – Sterling Heights, Clinton Township, Warren
Washtenaw County – Ann Arbor, Ypsilanti
West Michigan
Kent County – Grand Rapids, East Grand Rapids, Wyoming
Ottawa County – Holland, Grand Haven, Zeeland
Muskegon County – Muskegon, Muskegon Heights
Allegan County
Mid-Michigan
Ingham County – Lansing, East Lansing
Eaton County
Clinton County
Genesee County – Flint
Northern Michigan
Grand Traverse County – Traverse City
Leelanau County
Emmet County – Petoskey
Charlevoix County
Licensed in all 83 Michigan counties and headquartered in Troy. Local pages for Detroit, Ann Arbor, Lansing and the Michigan hub.
Jumbo loans in Michigan, answered.
The questions Michigan buyers ask us most about financing above the limit.
Where in Michigan do jumbo loans actually come up?
Wherever the loan, not the price, passes $832,750: Birmingham, the Bloomfields, parts of Troy and Rochester Hills, Ann Arbor, the Grosse Pointes, lakefront property across the state, and northern Michigan resort markets around Traverse City, Harbor Springs and Charlevoix. Because no Michigan county has a raised limit, the line is the same everywhere.
Should I put more down to stay conforming?
Often, yes. If your loan lands just above $832,750, increasing the down payment enough to slip under it usually gets you easier underwriting, lower reserve requirements and possibly a better rate. We run that comparison as a matter of course.
Are jumbo rates higher?
Not necessarily. Jumbo pricing has at times run level with or below conforming rates, because lenders compete hard for borrowers with strong credit and large balances. We quote both against your actual file rather than relying on the rule of thumb.
What are cash reserves and why do jumbo lenders want them?
Reserves are the money you still have after closing, measured in months of your new payment. Jumbo lenders typically want six to twelve months. Retirement and investment accounts usually count, often at a discount. Running savings to zero at closing is the most common reason a strong jumbo file stalls.
Can I finance a second home up north with a jumbo loan?
Yes. Jumbo financing covers second homes as readily as primary residences, which FHA and VA do not. Lakefront and resort properties sometimes need a closer look at the appraisal because comparable sales are scarce, and we plan for that from the start.
Get your Michigan jumbo quote.
Tell us the price range and roughly what you can put down. A licensed pro will confirm whether the loan is jumbo or conforming and come back with real numbers, usually the same business day.

Prefer to talk?
248-416-1361
Open 24/7. Ask for your pro by name.

Visit our office
880 W. Long Lake Rd, Suite 300
Troy, Michigan 48098, just off I-75. Free parking.

Licensed and reviewed
Michigan 1st Mortgage Broker/Lender License FL0023852. NMLS #1925352. Rated 4.9 across 5,200+ Google reviews.