Mortgage Broker in Detroit, Michigan
Detroit is a city of neighborhoods with very different price points, housing stock and appraisal realities. Financing here rewards a lender who has closed on streets like yours before and prepares the file for what the appraiser will find.
Headquartered in Troy, about 30 minutes up I-75. Licensed in 39 states. Rated 4.9 across 5,400+ Google reviews.
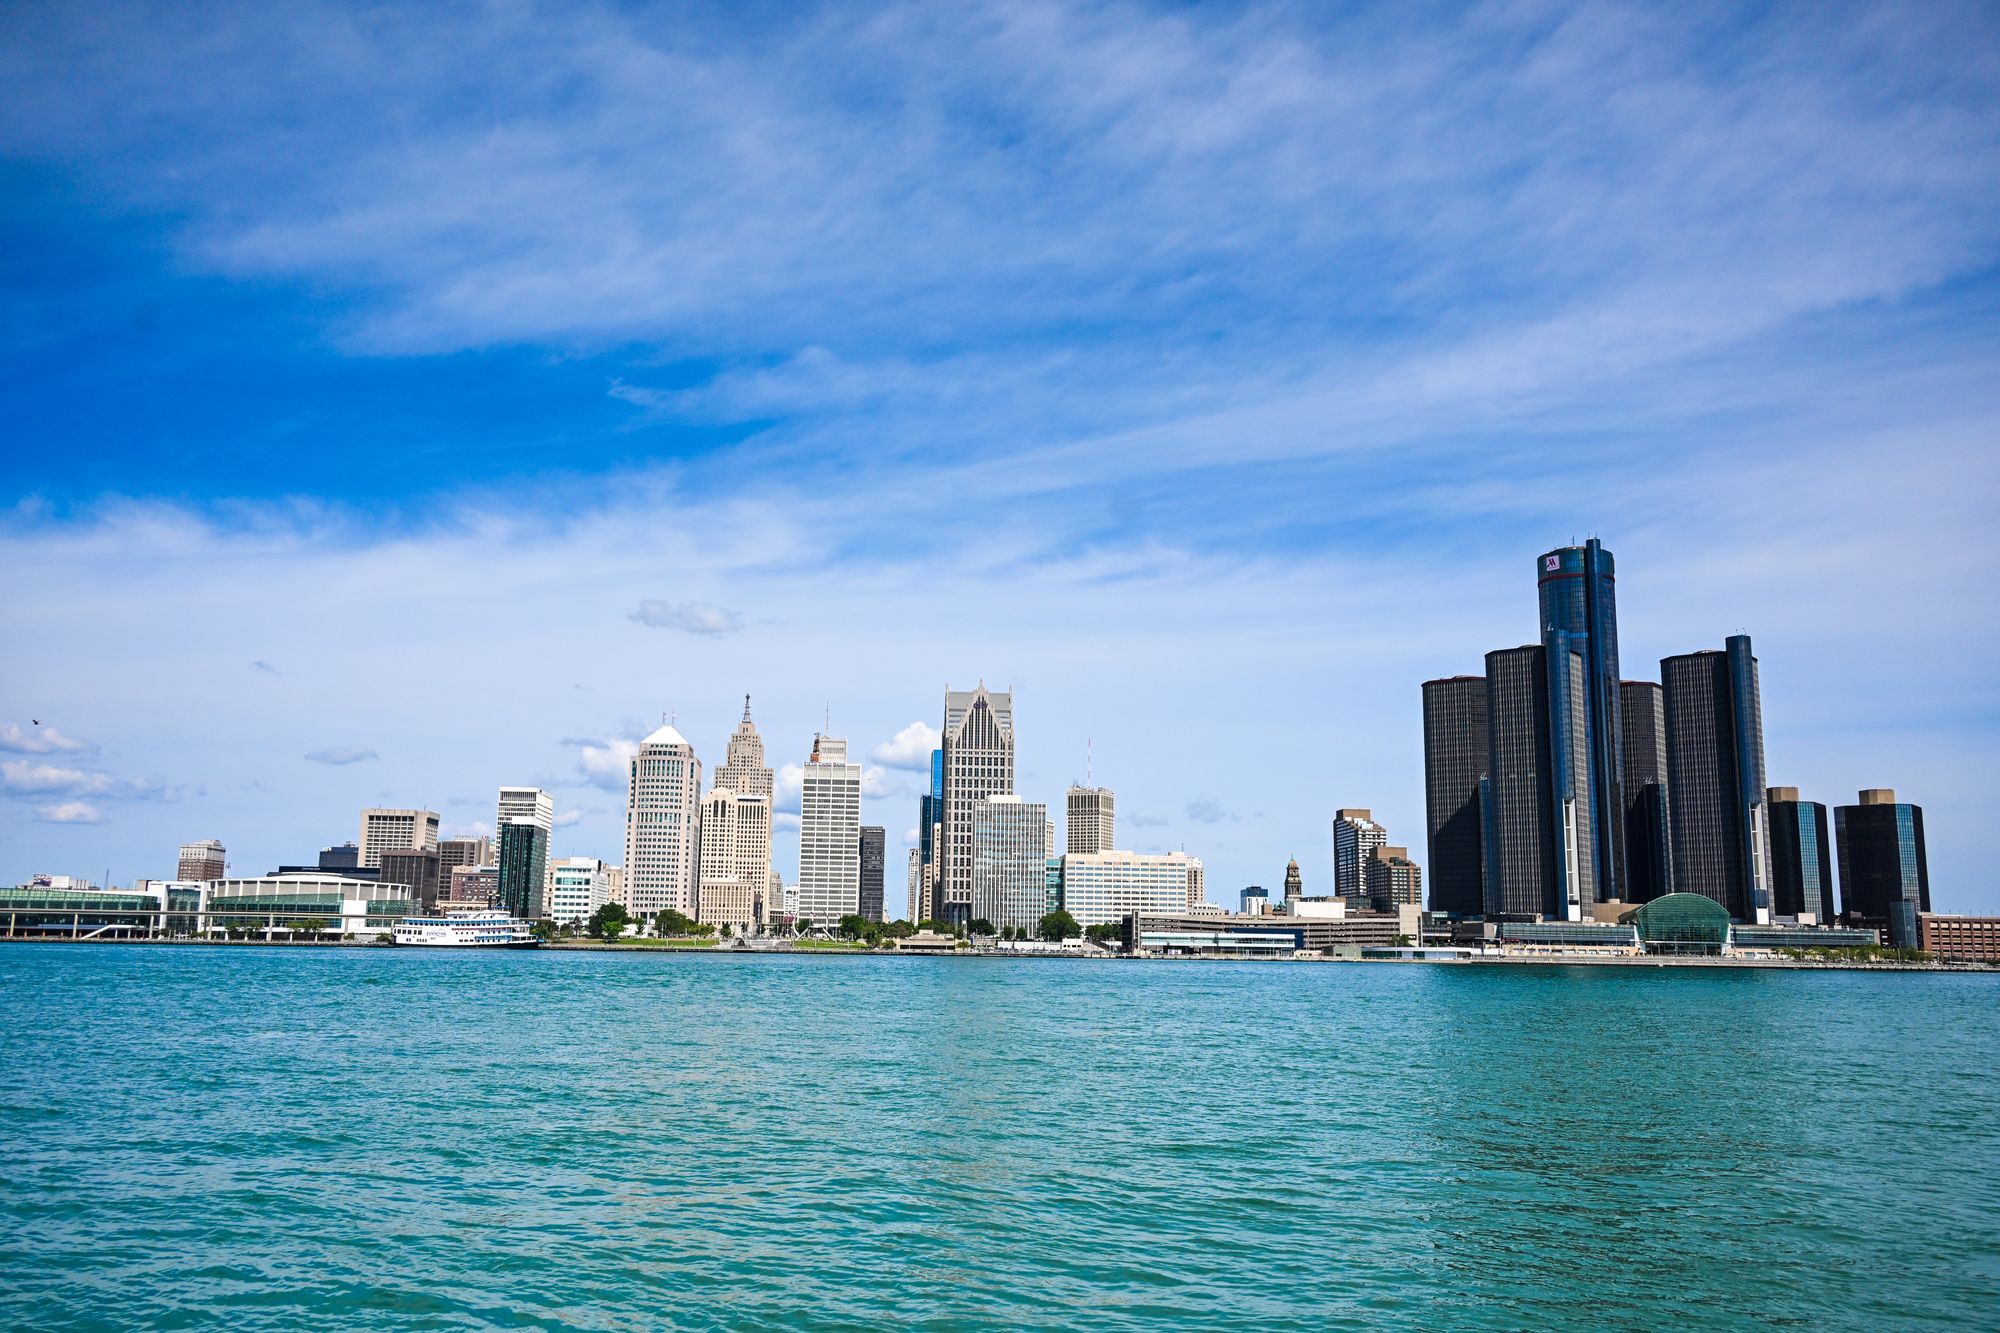
Detroit
Every neighborhood, every price point
2019
Founded in Troy, Michigan
300+
Licensed loan officers on the team
4.9
Average of 5,400+ Google reviews
39
States licensed, headquartered here
Detroit is not one market.
A brick Tudor in Boston-Edison, a bungalow on the east side, a loft in Corktown and a new condominium in Midtown can sit within a few miles of each other and belong to four different markets. Prices, condition and how easily a home appraises all change from one neighborhood to the next, which is why a lender who treats Detroit as one place gets Detroit wrong.
The appraisal is where that shows up most. In neighborhoods where values have risen faster than the record of comparable sales, an appraisal can come in under the agreed price. We order the appraisal early, prepare the file with the right comparables in mind, and know what the options are when a gap appears. The other Detroit-specific pieces of a purchase we handle routinely: designated neighborhoods carry Neighborhood Enterprise Zone property tax abatements that change your monthly payment; and homes bought through the Detroit Land Bank need financing matched to their condition.
Our office is in Troy, about half an hour north. In practice almost every Detroit client works with us by phone and e-signature, and closes at a title company in the city or with a mobile notary at home.
Detroit neighborhoods and Wayne County.
Where we have closed, and keep closing. The list is not exhaustive; if your street is not here, we still lend there.
Detroit neighborhoods
Downtown
Midtown
Corktown
Woodbridge
West Village
Indian Village
Boston-Edison
Palmer Woods
Sherwood Forest
University District
Bagley
Rosedale Park
Grandmont
East English Village
Morningside
Jefferson-Chalmers
Southwest Detroit
Green Acres
Wayne County
Dearborn
Dearborn Heights
Livonia
Redford
Grosse Pointe
Grosse Pointe Park
Grosse Pointe Woods
Harper Woods
Hamtramck
Highland Park
Taylor
Allen Park
Lincoln Park
Wyandotte
Westland
Garden City
Canton
Plymouth
Northville
Romulus
Licensed everywhere in Michigan and headquartered in Troy, Oakland County.
Every loan we write in Detroit.
One licensed pro is your point of contact from the first call to closing, and shops your file across the lenders we work with. Pick the product and we will price it for your situation.
Buying
Home purchase
A quick pre-approval, offers sellers take seriously, and every loan type priced side by side.
Lower your rate
Refinance
A lower rate, a shorter term or a fixed payment. We show you the break-even before you commit.
Use your equity
Cash-out refinance
Borrow against the equity you have built for a renovation, debt or an investment.
Most buyers
Conventional
From 3 percent down for eligible borrowers, with mortgage insurance you can cancel at 80 percent of the original value.
Flexible credit
FHA
From 3.5 percent down with credit scores from 580. The most common first-time buyer route.
Veterans
VA
No down payment and no monthly mortgage insurance for eligible veterans and service members.
Above the limit
Jumbo
For loans above the conforming limit, usually with no mortgage insurance.
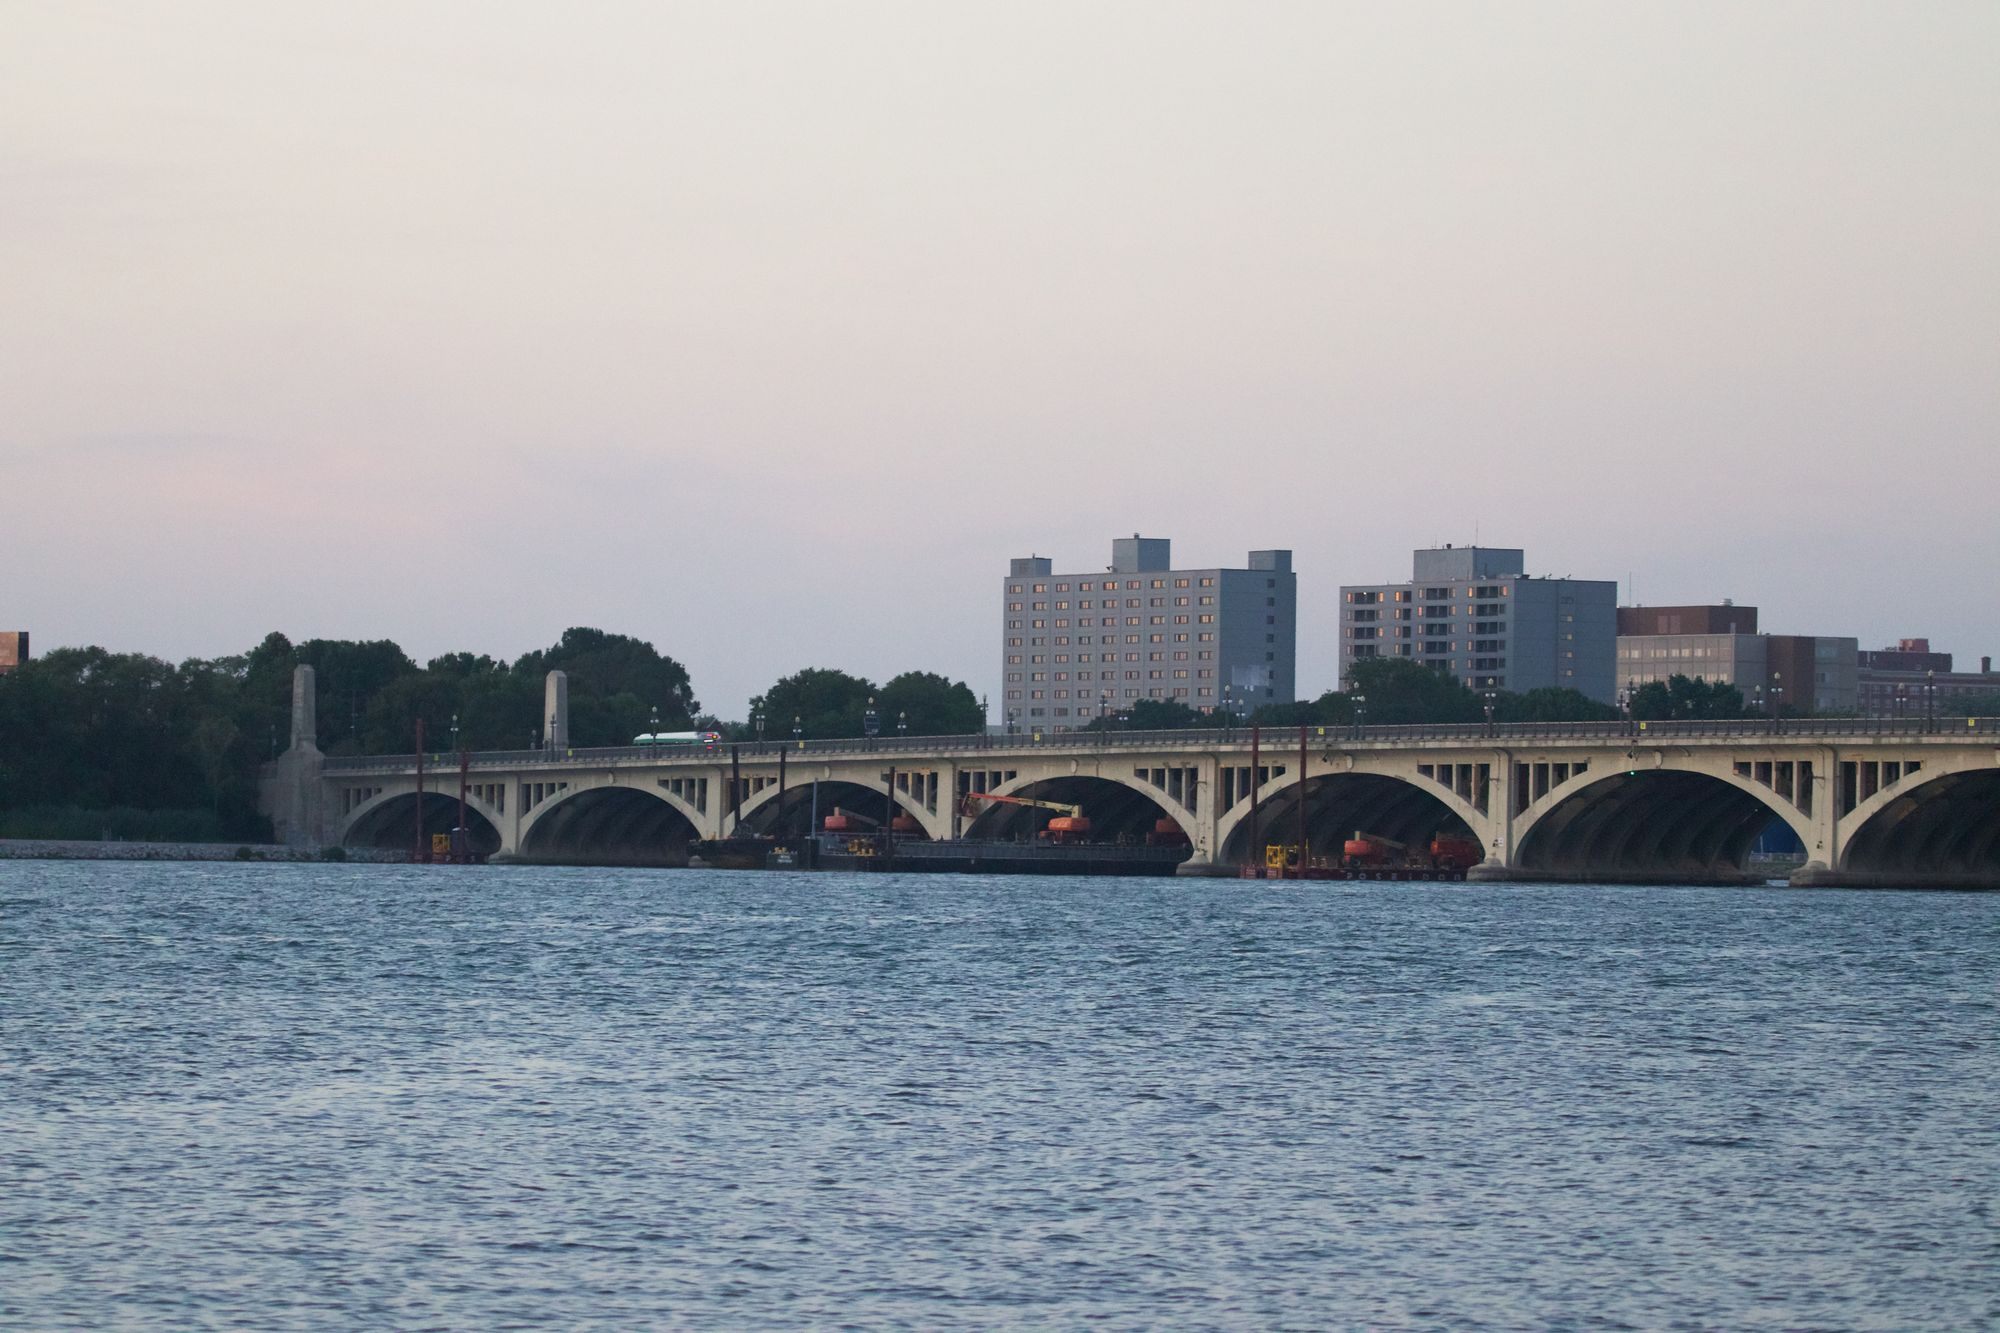
Belle Isle and the riverfront
Detroit’s neighborhoods price very differently. Your pro has closed on streets like yours.
Four things that are different about buying in Michigan.
They apply in Detroit as much as anywhere in the state, and the first one catches buyers from elsewhere off guard.
01
Your property tax bill resets when you buy
Michigan caps how fast a home’s taxable value can rise each year, and that cap comes off when ownership transfers. The seller’s bill reflects their capped value; yours will be based on the current state equalized value, which can be materially higher. Budget from the SEV, not the seller’s bill, and file the Principal Residence Exemption, which removes up to 18 mills of school operating tax on the home you live in.
02
Transfer tax is the seller’s cost by default
Michigan charges $3.75 per $500 of price to the state and $0.55 per $500 to the county, and the seller pays unless the purchase agreement says otherwise. Buyers pay recording fees and title charges instead, which are far smaller.
03
Loan limits are simple here
Every Michigan county uses the national baseline: $832,750 for a conforming loan and $541,287 for an FHA loan on a one-unit home in 2026. There are no high-cost counties in the state, so the limit is the same in Troy, Detroit, Lansing and Ann Arbor.
How it works from Detroit.
Four steps, one pro, and nothing that requires a trip to our office unless you want one.
1
Talk to a pro
A short call about what you want to do. We look at your situation and give you an honest read. No hard credit pull until you are ready to move forward.
2
Get real numbers
Your pro shops the lenders we work with and comes back with actual rates and costs, explained line by line, so you can compare against anyone else.
3
We prepare the file
Documents gathered once, the appraisal ordered early, and any Michigan-specific item handled, such as the Principal Residence Exemption and the uncapping of property taxes.
4
Close where it suits you
Purchase closings commonly take 30 to 45 days, streamline refinances often need less paperwork, and timelines vary with the appraisal, title and underwriting. You can sign at our Troy office, at the title company near you, or with a mobile notary at your kitchen table.
Ready to buy or refinance in Detroit?
A licensed pro who knows the city’s appraisal realities quotes your options. Free, and it starts without a hard credit pull.
Questions we hear in Detroit.
If yours is not here, a licensed pro who works the city will answer it directly, with no obligation.
What happens if the appraisal comes in low?
It happens in Detroit more than most places, because in a fast-improving neighborhood the recent sales an appraiser must use can lag the price you agreed. The usual paths are a price renegotiation with the seller, a larger down payment to cover the difference, a reconsideration of value with better comparables, or, on some programs, a second appraisal. We prepare for it from the start rather than being surprised at the end, and we walk you through the choice if it lands.
Can I finance a Detroit Land Bank home?
Often, and it depends on the property’s condition. A Land Bank home that is habitable and meets the loan program’s property standards can be financed like any other purchase. One that needs significant work before it is livable needs financing matched to renovation, and we will tell you plainly which side of that line a specific house falls on before you commit.
What is a Neighborhood Enterprise Zone and does it change my payment?
The NEZ is a City of Detroit property tax abatement for homes in designated areas, and it can lower the tax portion of your monthly payment for a period of years. The city administers it, not the lender, so confirm the designation and its remaining term for the specific address. We include the abated figure in your payment estimate once it is confirmed.
Can you finance a condominium downtown or in Midtown?
Yes. Condominium financing turns on the building as much as the buyer: the association’s finances, owner-occupancy and insurance all get reviewed. Most established downtown and Midtown buildings are straightforward; newer conversions sometimes need a closer look. We ask for the association documents early so there are no surprises in underwriting.
Do I have to come to your Troy office?
No. Almost every Detroit client works with us entirely by phone, email and e-signature. Closings are arranged at a title company near you or with a mobile notary who comes to you. The office is there if you want it, about 30 minutes north on I-75, with free parking.
Talk to a pro about Detroit.
Tell us what you are looking to do. A licensed pro who works this market will call back, usually the same business day. Asking does not start a loan or require a hard credit pull.

Prefer to talk?
248-416-1361
Open 24/7. Ask for your pro by name.

Visit our office
880 W. Long Lake Rd, Suite 300
Troy, Michigan 48098, just off I-75. Free parking.

Licensed and reviewed
Michigan 1st Mortgage Broker/Lender License FL0023852. NMLS #1925352. Rated 4.9 across 5,400+ Google reviews.